The limited partners who provide the capital to venture firms — the “money behind the money” — are feeling great right now. They’re in uncharted territory in many ways, but also potentially exceedingly lucrative territory.
Normally, LPs typically spread their bets across many firms to diversify their own portfolios. They write checks to emerging managers and established ones, to generalist firms and specialists. The goal is a strong return, but also to minimize risk.
That’s the typical playbook. But typical is out the window. OpenAI and Anthropic’s valuations have shot up so quickly that nearly everyone has piled into the same two companies on the way up, often inside the same venture firm, despite the longstanding venture convention of avoiding investments that conflict with one another. No one is complaining, either. The LPs I speak with seem unbothered by this big gamble, given the potential returns; they’re expecting a bonanza.
But they do see danger ahead, even if they describe this as a “yellow light” situation, and they’re uneasy about how quickly VCs are coming back to raise new funds.
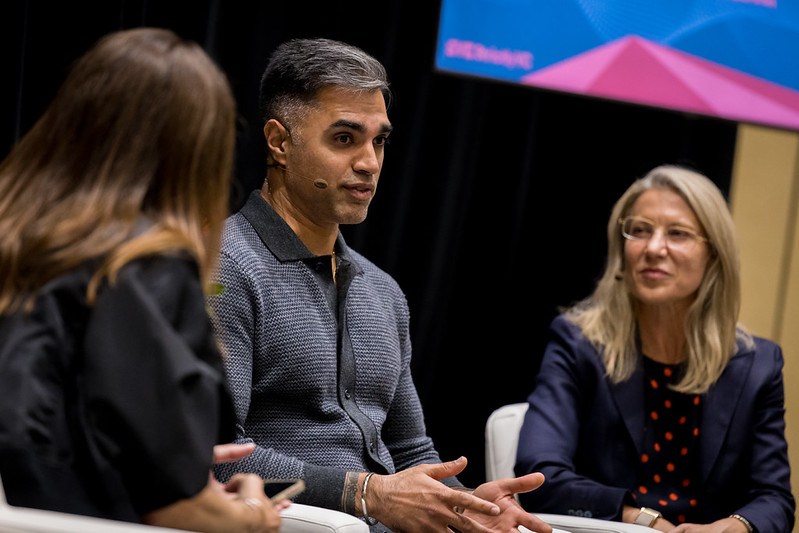
I talked about all of it recently with Beezer Clarkson of LGT Capital Partners, a Zurich-based diversified asset manager, and Amit Bhatti of TrueBridge, a Chapel Hill firm that focuses solely on venture. This conversation has been edited for length.
These are strange days — exciting but also scary. How are you feeling about your roles right now, and your place in this startup ecosystem?
Beezer Clarkson: It’s very busy, but I wouldn’t say it’s scary. There’s a lot of change and a lot of variables at play. I love venture, so I find the chaos fun. I’ve been doing this for a couple of decades, so seeing the cycles makes it less scary. You appreciate that these things happen, and that we should enjoy the upside, because sometimes there’s downside, and the up is a lot more fun than the down.
Amit Bhatti: If anything, it’s exciting. Venture is sometimes looked at as a niche, and now that AI is all-consuming, all the attention is on venture. This feels like our moment more than it is like, “Oh gosh, what’s going to happen?” The pace of investing and the valuations may be different, but really meaningful stuff is happening, and all the attention is focused on this corner of private equity.
Your funds all hold the same brands now, OpenAI and Anthropic, multiplied across however many funds you back, and your job is to keep your institutions diversified. How do you think about that? Obviously it’s great right now, but if things turned, it would be less great.
Amit Bhatti: Venture has always been a power law business, so I actually view the concentration as a good thing. If we were getting to the maturity of one of our funds and there were still lots of tiny positions, something’s gone wrong. Our funds that are 10-plus years old are starting to consolidate into a few names. There’s a lot of Databricks, a lot of SpaceX, a lot of Stripe. In this generation of funds, I would hope there’s a lot of Anthropic and a lot of OpenAI. That’s a feature, not a bug. Not every one of these companies is going to work out, but that consolidation is typical. What’s different is how quickly it’s happened. I don’t view it as an immediate panic signal.
Beezer Clarkson: At the early stage, you still see quite a diversity of opportunity sets, and the dollars are smaller. It aggregates up into the same companies, but early-stage funds obviously aren’t doing the big late-stage stuff, so you have more diversity there, if that’s what you’re looking for.
Funds that invested on four-year cycles have shrunk that to three, then two, then 18 months. Is the pacing okay, or is it concerning?
Beezer Clarkson: We’re seeing funds come back on one-year pacing, which is fast. The norm was probably two to two and a half years. Some funds are deploying much faster because they’re taking concentrated, big-check positions. That could be a worrisome sign. It could work out, we don’t know, but it’s typically harder to do a one-year vintage and get it right.
Amit Bhatti: Similar for us. I would have said 24 to 36 months was roughly normal. Now 12 to 18 is not crazy for some of the funds going really quickly. A lot of funds are bumping up their fund sizes mid-cycle, which is definitely unusual. That’s partly because rounds have gotten so large. If Anthropic is raising a giant quantum of capital and you put 20% of the fund into it, you’re obviously going to be ahead of pace. Seed round sizes have gone up almost 2x, too, so if you want to lead, you’re writing 2x the check. It’s definitely a yellow light. It gives us a little bit of heartburn.
But when we look at what these managers actually bought, the numbers are different. The last time we had accelerated pacing, there was a lot of investing in zero-revenue crypto moonshots. Now we’re seeing a lot of companies go from zero to $100 million in revenue, which was totally unheard of before.
If you’ve got a great manager who comes back every year but the returns are still on paper, can you say “call me next time,” or do you lose your seat at the table?
Beezer Clarkson: It’s very hard to leave a manager and then come back. It happens, but it’s more typical to downsize your check. In 2021, a lot of LPs said, “If I was going to give you $10 million, I’ll do $5 million, because $10 million was for two years.” In our portfolios, the pacing gets pulled through, so we think about our pacing as well as yours.
Amit Bhatti: Same here. We’re building out a calendar of when we expect to make commitments, so if someone goes way off that map, we need to make sure the capital is there. You see people downsize or communicate it up front. It’s hard to say you’re sitting it out altogether, because then you’re not reliable capital. That’s also why you’re seeing upsizes; managers don’t want to come back and say they’re raising a whole new fund, so they bump up the old one.
Beezer Clarkson: People also rotate out of venture sometimes because capital calls keep running with no distributions coming back, and they still have to meet operating commitments, whether it’s the endowment, the hospital, or the foundation. That puts a lot of strain on those situations.
LPs like time diversification, yet a lot of funds were raised in recent years, including that backed startups at high valuations during the pandemic. How are those funds doing, and how would you describe 2026 so far?
Beezer Clarkson: The 2021 vintages are still early, five years in, but they argue against doing one-year funds. Some will catch a piece of an AI company and look excellent, but your odds of getting it right in one year are just tougher, and the valuations were extreme.
Amit Bhatti: If I look at the last 15 years of our portfolio, I wouldn’t bet on the COVID vintage being the best one. But a couple of breakouts will come from it. OpenAI was around in that era, and Cursor started pretty far back, so they’re in some of those funds. And liquidity has started flowing. The past two years were definitely slower, but SpaceX is the headline, Cerebras was a big exit this year, there have been a couple of other IPOs, and a lot of M&A. We’re seeing $10 billion-plus M&A exits, a $60 billion one [with Cursor]. Liquidity is going beyond just IPOs.
How are your venture fund managers thinking about secondaries? If I were a VC, I’d have been tempted to take money off the table in OpenAI or Anthropic.
Beezer Clarkson: Secondaries have become much more sophisticated in venture over the last, call it, five years. It’s localized in the top handful of companies, but it’s much more prevalent than before, which I think is good, because the ecosystem needs liquidity options. Venture is predicated on that, and if you wait 20 years for an IPO, that is not what structurally we all thought it could be. They’re also happening at multiple levels now. LPs sell stakes of their GPs, a strip of their portfolio, and the taboo around it is less.
Amit Bhatti: It’s the third leg of liquidity now: IPOs, M&A, secondaries. Private equity has always had a well-developed secondaries market, and venture didn’t. It was kind of a dirty word. You were only selling if you were distressed. Then people were holding the bag in 2021 and thought, “I should have sold.” Now more managers use it as a tool, and more judiciously. If you still believe it’s the power law company, you’re probably not exiting the whole position. But if you can sell 20% of your position and return your fund, you should probably do it.
There’s a lot of founder selling and employee tenders — often very early into the company’s “journey.” How do you feel about that?
Amit Bhatti: We were talking before about the analogy to crypto, where things got very difficult in part because employees were paid in tokens that were liquid immediately. What’s your motivation to stick around when things get hard? So I think it’s great that there are employee tenders, especially for companies that have been around a long time, like Stripe and Databricks, with a very clear financial picture. For them to offer partial liquidity to employees is totally reasonable. But a lot of the enforcement falls on the lead investors. Investors we back have told companies, “We don’t want you to do an employee tender right now.” Those conversations are happening behind the scenes, and people have learned some lessons from last time. It’s all based on leverage, though. If the founder has incredible leverage . . .
When these companies go public and employees get liquid, will they become partners or competitors to your venture managers? These employees have amazing networks.